
The sales of industrial robots in the Chinese market account for over 50% of the global market, and the market share of domestic brands continues to rise
author: Hansheng Automation
2023-05-19
The "Implementation Plan for" Robot+"Application Action" recently issued by 17 departments including the Ministry of Industry and Information Technology points out the need to deepen the application of "robot+" in key areas.
It is proposed that by 2025, we will focus on 10 key application areas, break through more than 100 innovative application technologies and solutions for robots, promote more than 200 typical application scenarios of robots with high technological level, innovative application modes, and significant application effects, and create a group of "robot+" application benchmark enterprises.
It is proposed that by 2025, we will focus on 10 key application areas, break through more than 100 innovative application technologies and solutions for robots, promote more than 200 typical application scenarios of robots with high technological level, innovative application modes, and significant application effects, and create a group of "robot+" application benchmark enterprises.
The previous "14th Five Year Plan for the Development of the Robot Industry" showed that by 2025, the average annual growth rate of the robot industry's revenue will exceed 20%, and the density of manufacturing robots will double. Data shows that in 2020, the density of robots in China's manufacturing industry was 246 units/10000 people, which means it will reach around 500 units/10000 people by 2025, and the market space is very huge.
Emerging industries are the main field for industrial robot shipments
According to statistics, in 2022, the sales of industrial robots in the Chinese market exceeded 300000 units, accounting for over 50% of global sales. Despite the severe impact of the epidemic, achieving such results is not easy.
From the perspective of the application industry, it is mainly driven by the demand of emerging industries such as new energy vehicles, lithium batteries, photovoltaics, semiconductors, and healthcare. The trend of new energy explosion is not decreasing, and the market production and sales are booming. Major well-known new energy vehicle companies are expanding production capacity, driving the market's demand for lithium batteries. According to statistics, the shipment volume of industrial robots from new energy vehicles and emerging industries accounts for over 40% of the overall market.
In the past year, the 3C electronics industry has shown sluggish performance, with electronic products such as smartphones in a high inventory state. Reduced demand has forced manufacturers to frequently cut orders, leading to a significant decline in demand for industrial robots; General industries have also been affected by macroeconomic downturn, rising commodity prices, and poor supply chains, although there has been some recovery, it has not been as expected.
During this year's Spring Festival, the sales revenue of consumer related industries nationwide increased by 12.2% year-on-year, and the offline and online consumption situation has significantly improved. The market is optimistic about the recovery of the consumer electronics market, and the supply side inventory is gradually decreasing. The shipment of related industrial robots has also increased. However, based on the current market situation, whether it really bottoms out and rebounds still needs to be verified.
In 2023, with the comprehensive opening up of the epidemic, the overall recovery trend of the market is obvious. As a key product driving industrial upgrading, industrial robots have not changed their long-term trend of positive development, and will maintain double-digit growth in the coming years. Among them, the new energy vehicle industry will undoubtedly have the greatest demand.
According to data from the China Association of Automobile Manufacturers, in 2022, China's new energy vehicles continued to experience explosive growth, with annual sales exceeding 6.8 million units and market share increasing to 25.6%. They are gradually entering a period of comprehensive market-oriented expansion, with plans to increase to 50% by 2035. Not only China, but also the United States has proposed to achieve a penetration rate of 50% by 2035, while the European Union is more aggressive, expected to increase to 100% by 2035, and stop selling all fuel and hybrid vehicles.
Although new energy vehicles are similar to fuel vehicles, they also have many different processes, and their automation level is higher than that of fuel vehicles. This means that new energy vehicle production lines need to be built, or large-scale renovations and expansion of existing production lines will be carried out, which will bring about a huge demand for industrial robots.
Domestic robot market share continues to rise
After years of development, China's robotics industry has basically formed a full industry chain system from components to complete machines, and then to integrated applications. The innovation of core technologies and key components has been orderly promoted, and domestic robots have entered a turning point. It is expected to gradually move from replication to technology leadership, and from domestic substitution to overseas expansion.
In the past year, domestic manufacturers have relied on supply chain advantages and flexible pricing strategies to accelerate penetration in fields such as lithium batteries, photovoltaics, semiconductors, and automotive components. At the same time, relying on local advantages, they have gradually expanded more new application fields downstream of the industry, explored broader incremental market space, and further expanded the market share of domestic robots.
However, foreign manufacturers, due to the impact of the epidemic, have caused supply chains to be sluggish, supply cycles to be greatly extended, and they have not been able to match market demand in a timely manner. The market share has gradually decreased, and it was not until recently that there has been an improvement, and production and delivery have gradually resumed.
As a result, foreign manufacturers are accelerating the localization process of robots. In December last year, ABB's robot super factory in Shanghai officially opened, and in the future, 90% of China's industrial robot orders will be produced here; Fanuc's super intelligent factory located in Baoshan District, Shanghai has also begun to take shape and is expected to be completed and put into operation within the year, greatly enhancing its delivery capacity.
As the localization process of foreign brands from supply chain, research and development to production deepens, the localization advantages and cost control advantages of domestic manufacturers will also be weakened. Therefore, in order for domestic robots to maintain competitiveness, it is necessary to raise technical barriers, continuously optimize the quality of robot products, and accelerate the pace of catching up with overseas industrial robot brands.
Youao Robot: Only by implementing applications and truly solving industry problems can we usher in a new outbreak
Eston incentivizes 10 million shares to change the image of a "profit insulator"
Related Article

In order to create new products that are constantly emerging on the market, we use different methods to process various materials.
What is Molding Processing? We will introduce some representative molding processing methods

In the context of vehicle electrification and intelligence, human-computer interaction with consumer experience and intelligent control as the core has become an important development theme of intelligent cockpits. The on-board display is at the core of the intelligent cockpit, benefiting from the continuous development of the Internet of Vehicles and smart cars, the on-board display will usher in new development opportunities.
Lighting up new opportunities for automotive electronics - all at the 2025 Guangzhou International Automotive Intelligent Cockpit and Vehicle Display Technology Event

The 2025 Asia International Power Semiconductor, Materials and Equipment Technology Exhibition will focus on "Focusing on Cutting-edge Technology Breakthroughs and Empowering Industrial Innovation and Integration". It will be held on November 20-22, 2025 at Guangzhou Poly World Trade Center Expo!
Focus on the power semiconductor industry - APSME 2025 Asia International Power Semiconductor, Materials and Equipment Technology Exhibition will be held in Guangzhou
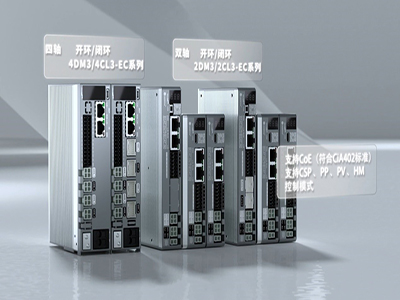
Lexey's multi-axis bus stepper drivers – 2DM3/2CL3-EC (open/closed-loop) dual-axis series and 4DM3/4CL3-EC (open/closed-loop) four-axis series are innovative technologies designed to solve the above problems and help your equipment to achieve efficient upgrades.
"Three provinces" drive: Leisai multi-axis bus stepping, opening a new chapter in the miniaturization and upgrading of precision equipment